
Home / Insurance Claim Roof Documentation
Insurance-Claim Roof Documentation, Done Honestly
Storm or hail damage is stressful. We make the roofing side simple — documenting your damage clearly so your claim stands on solid evidence.
Storm or hail damage is stressful. We make the roofing side simple — documenting your damage clearly so your claim stands on solid evidence.
In Spring, TX? See our Spring insurance claim documentation page for neighborhood-specific details.
We document your roof with drone and ground photos, identifying storm or hail damage.
Measurements and a written, itemized contractor estimate you can share with your insurer.
We provide the documentation and answer the construction questions your adjuster may have.
Once your claim is approved, we complete the work and provide full closeout documentation.
Inspect & document damage · provide measurements & estimates · provide evidence for your claim · complete approved work with warranty.
Negotiate your claim · act as a public adjuster · promise approval, payouts, or deductible waivers · make legal promises.
Start with a free, documented roof inspection. We'll tell you honestly what we find.
Tell us what happened. We'll schedule a free, documented roof inspection and give you an honest contractor estimate you can share with your insurer — no pressure, no public-adjuster games.
Drone and ground photos of your roof at no cost.
An itemized contractor estimate for your claim file.
We tell you plainly whether you have storm damage.
Full service in English or Spanish.
We'll confirm a time on a business day.
Insurance language can be confusing. Here's plain English on the terms homeowners ask us about most, so you always know where your claim stands. Remember: we're your roofing contractor, not a public adjuster — your insurer decides your claim.
The portion of the repair you pay, set by your policy. By Texas law (Ins. Code Chapter 707) a contractor cannot waive or absorb it — anyone who offers to is a red flag.
See how a deductible works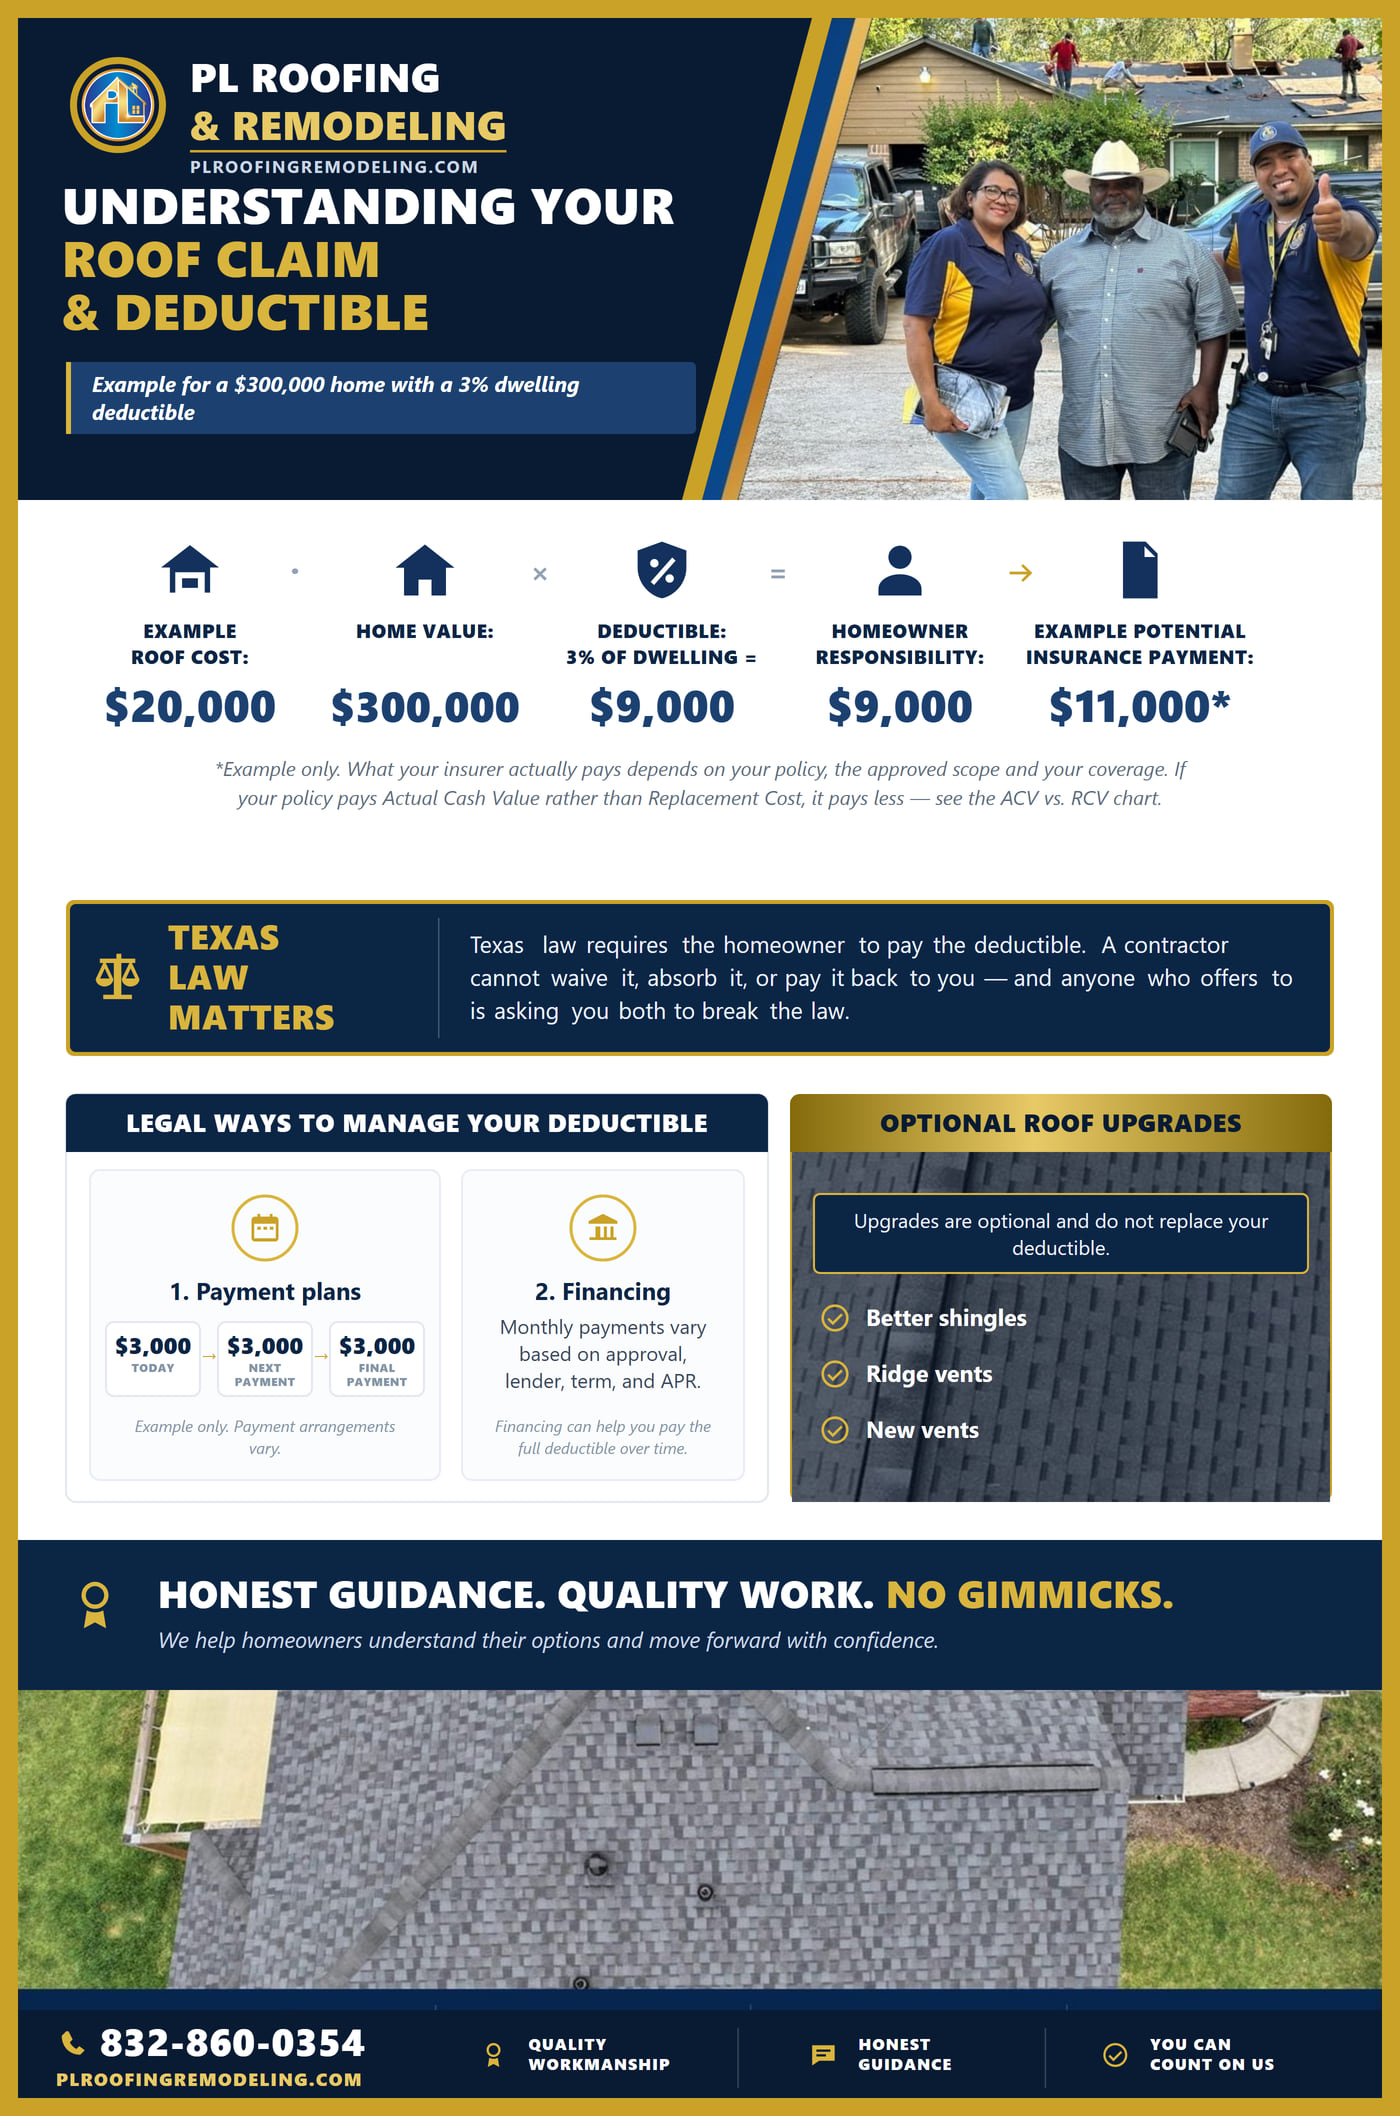
Actual Cash Value is the depreciated amount; Replacement Cost Value is the full cost to replace. Many policies pay ACV first and release the rest once the work is completed.
See the ACV vs. RCV chart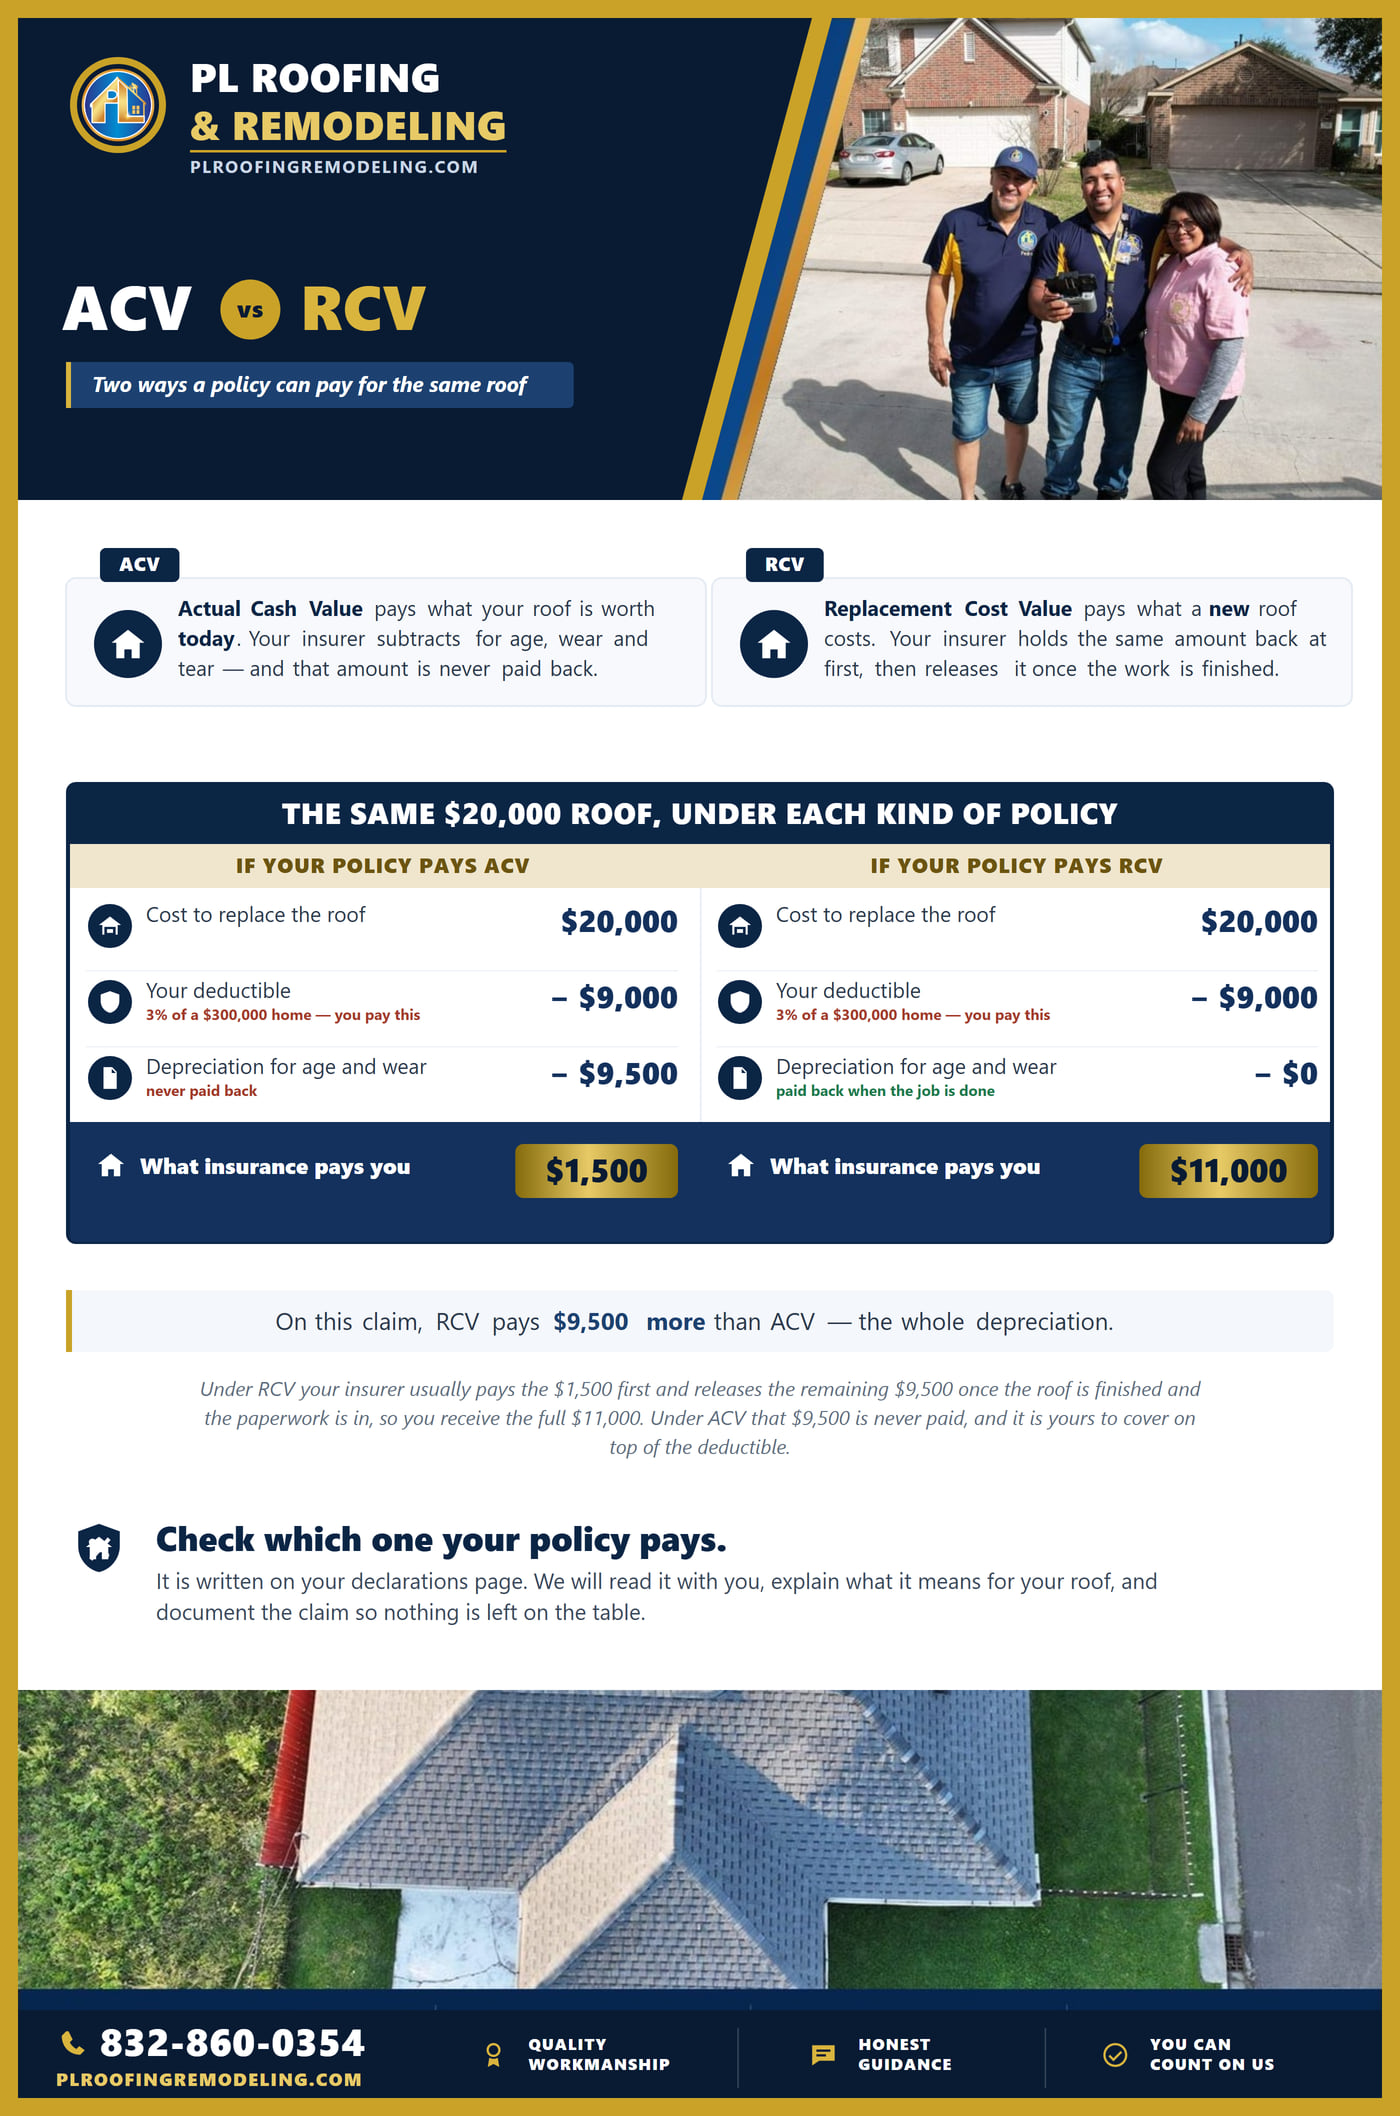
The amount your insurer holds back and releases after repairs are finished and documented. We provide the closeout paperwork that helps you recover it.
See how the second payment works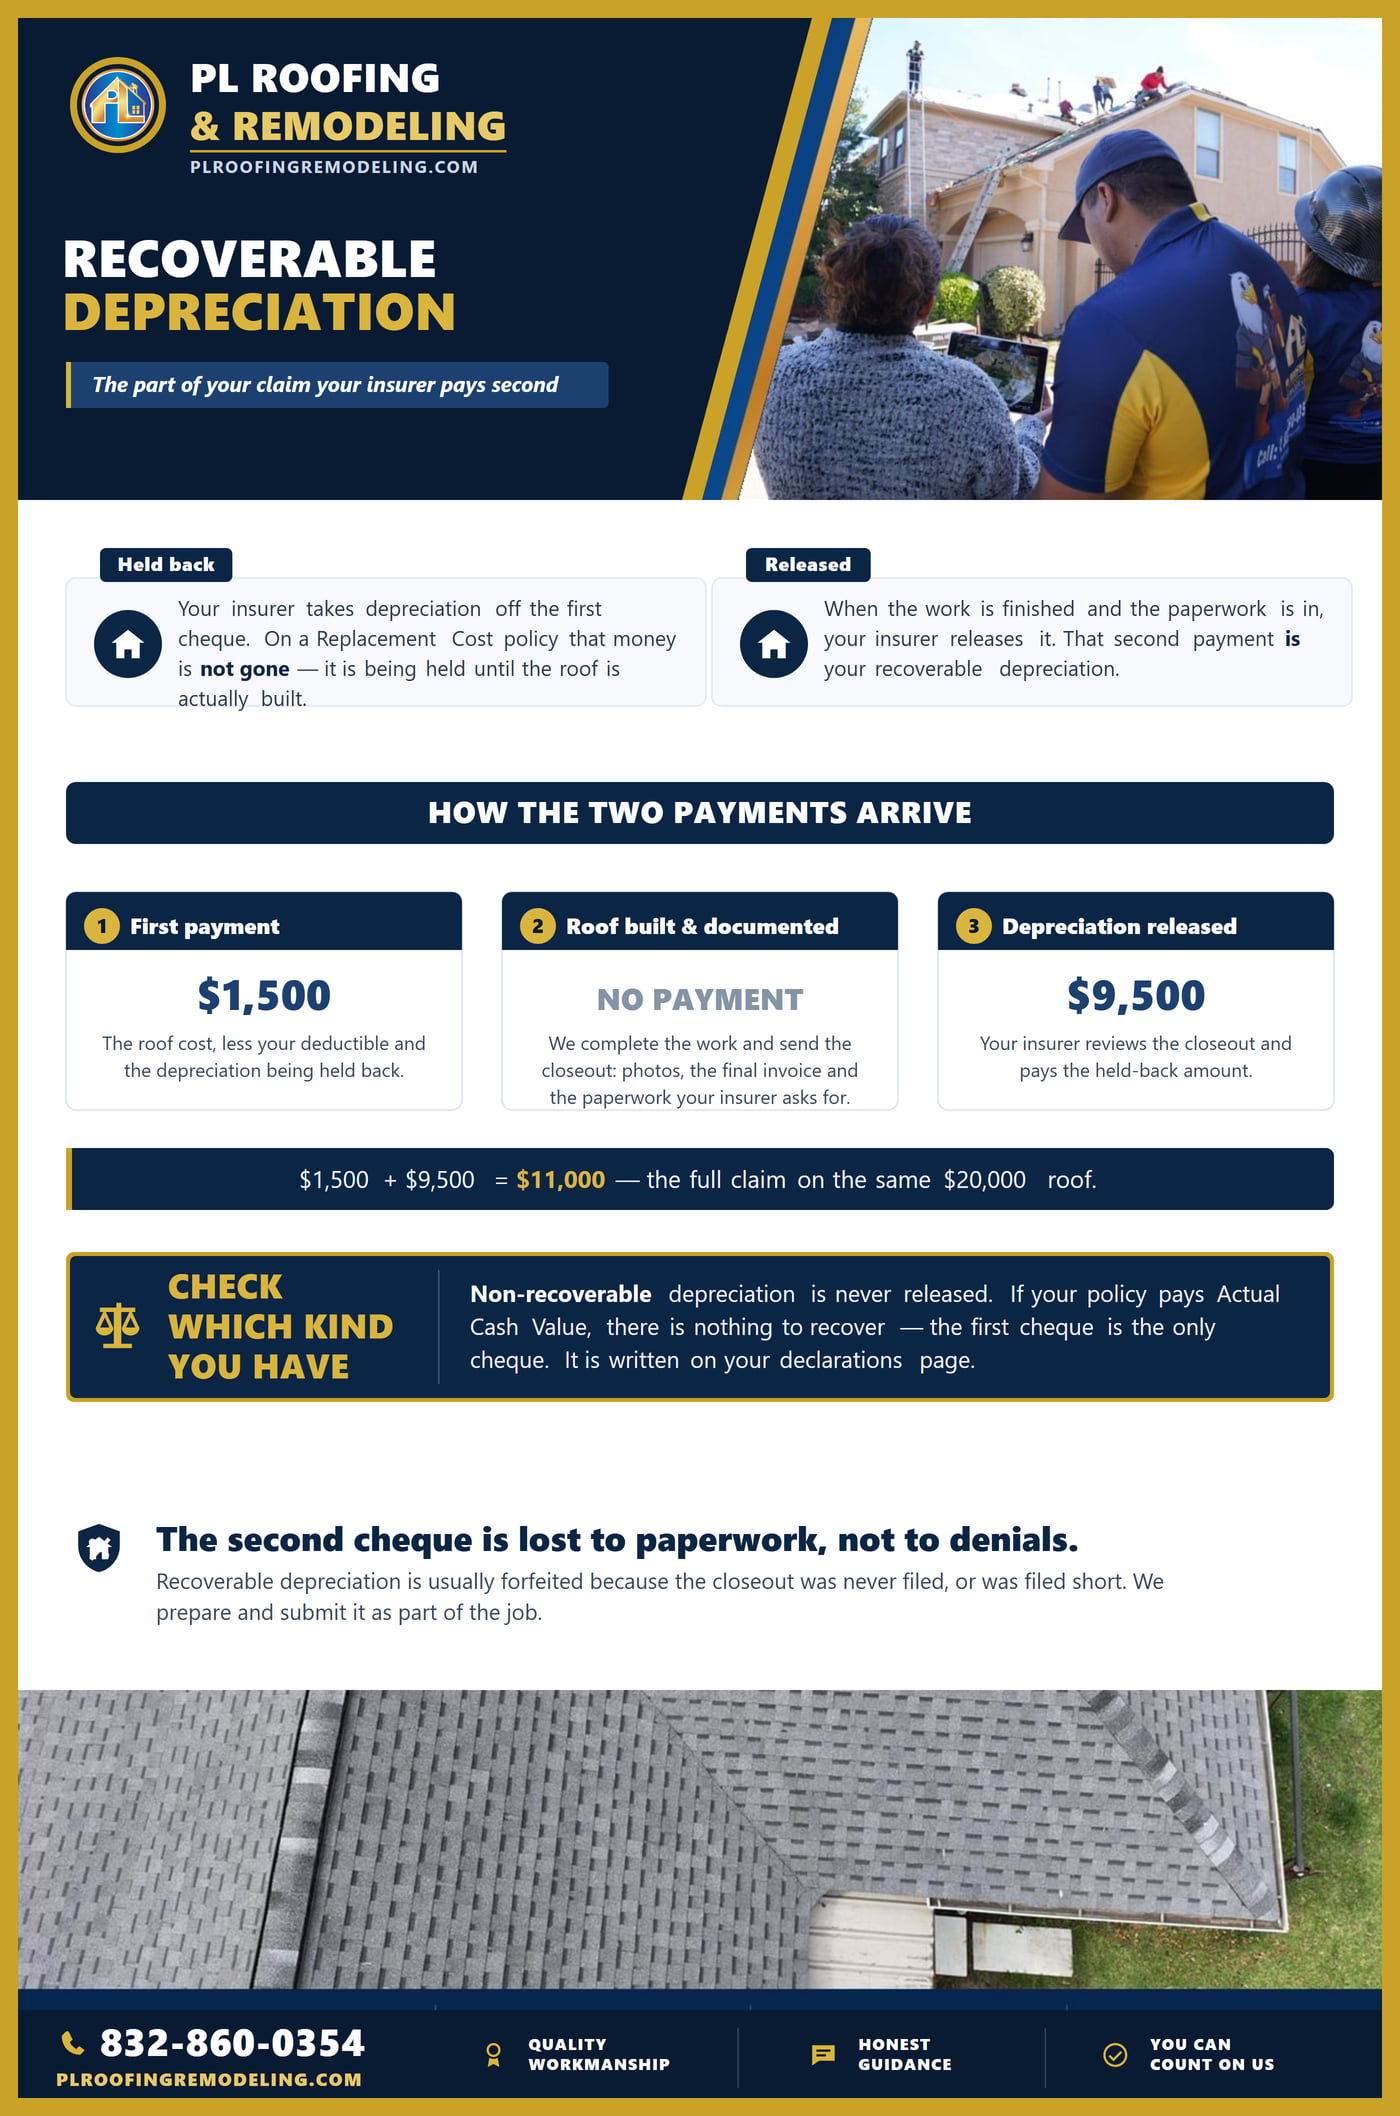
If the adjuster's scope misses damage or code-required items, we document it and prepare a supplemental estimate, with photos and measurements, for your insurer to review.
See how a supplement is built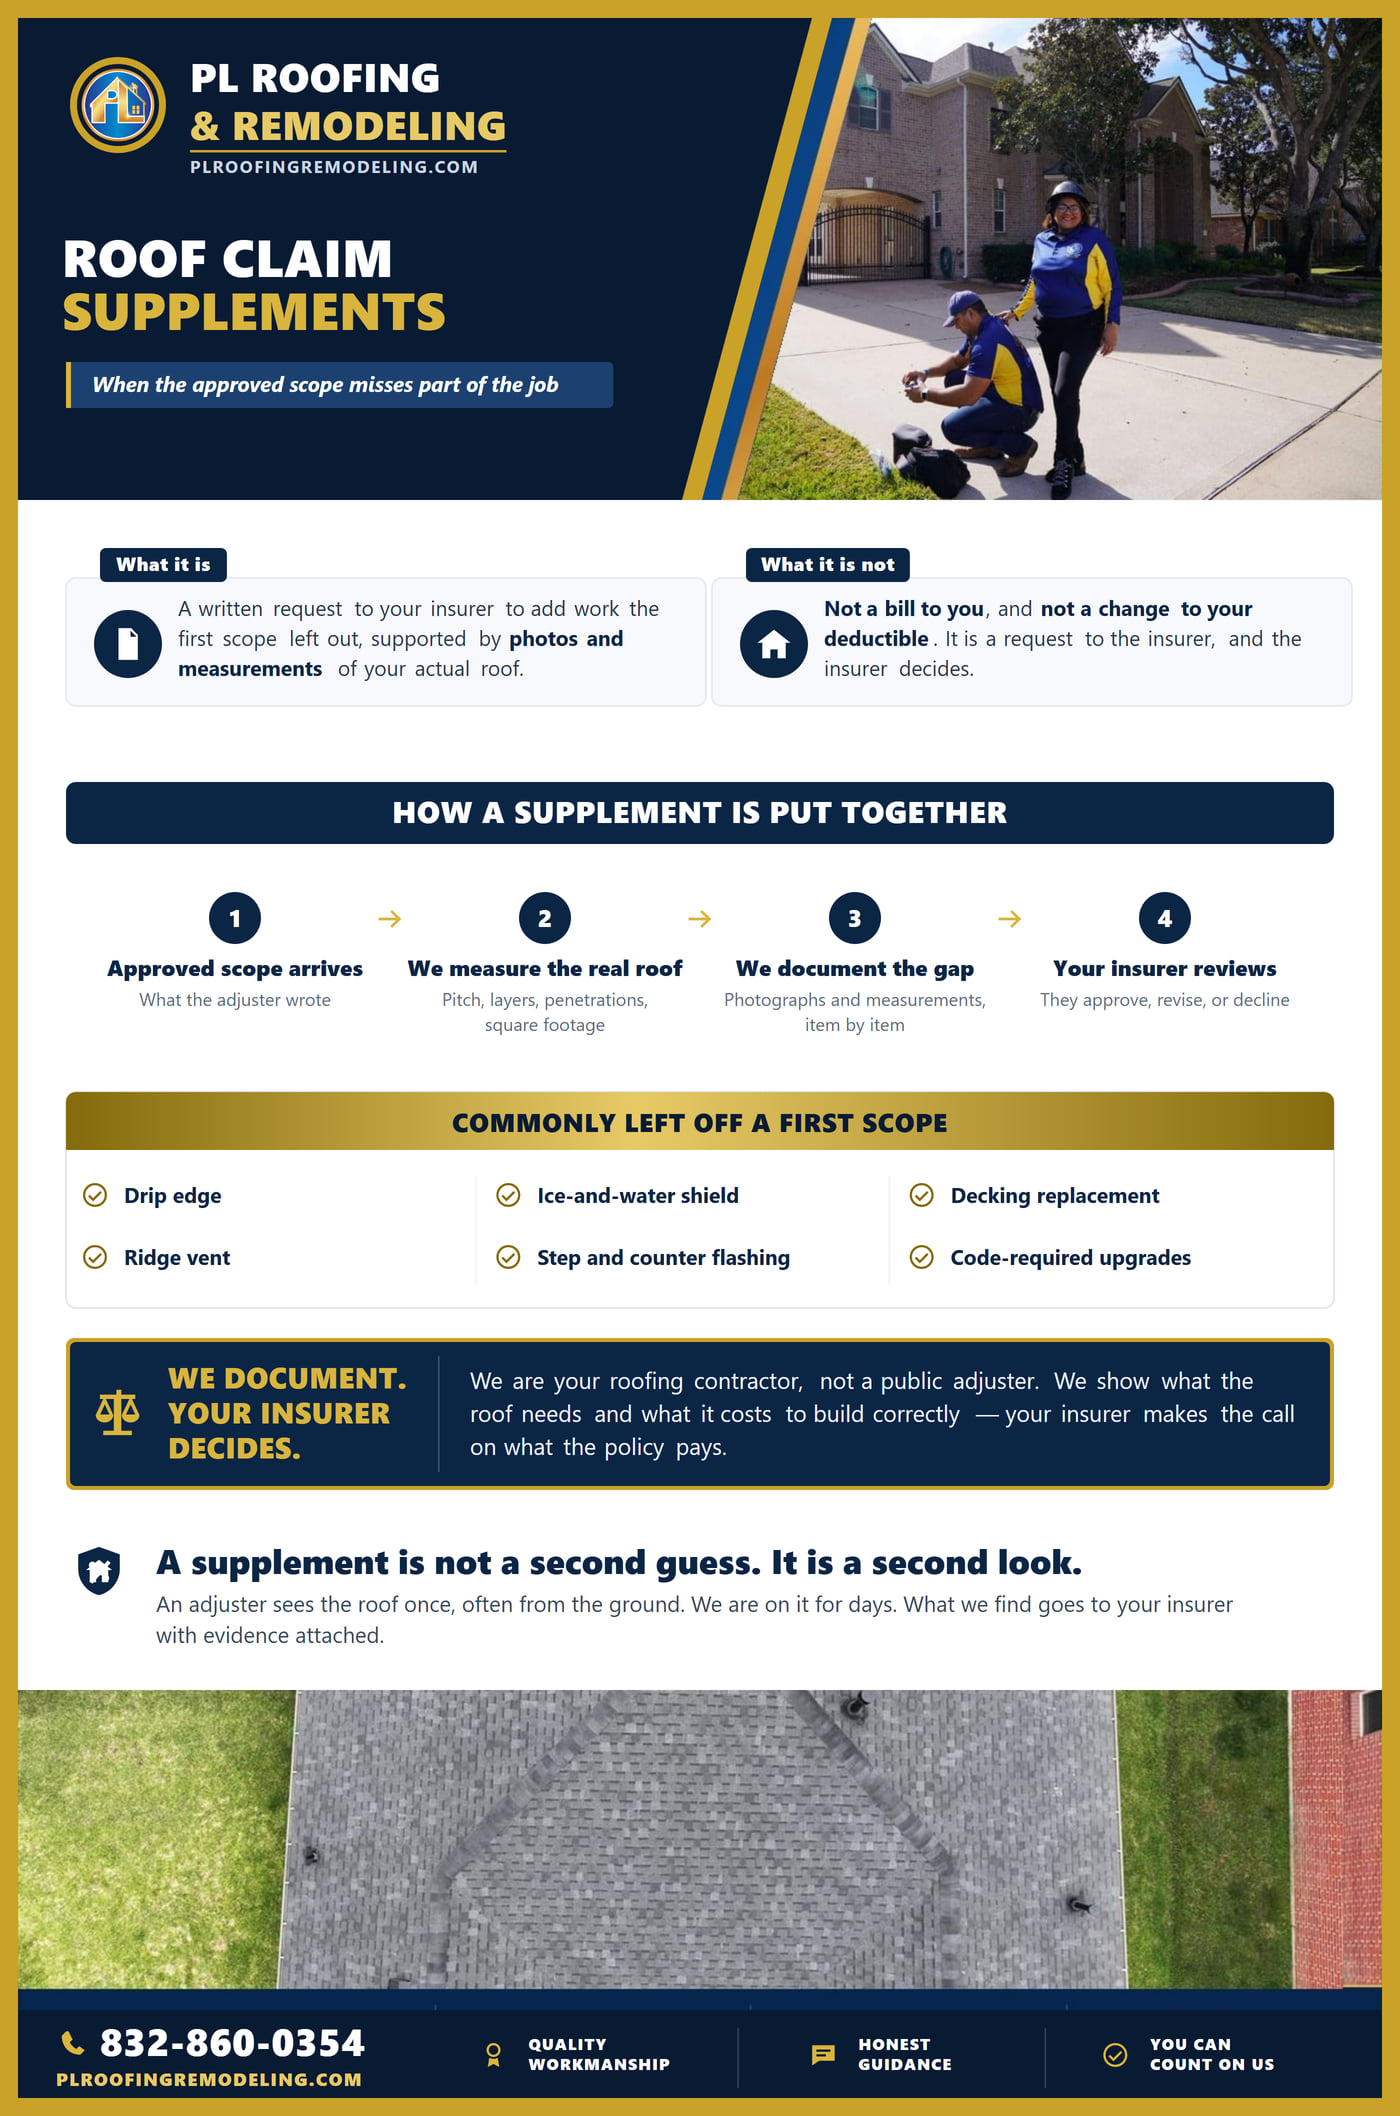
We inspect and document the damage; you file the claim with your carrier.
At your request, we can be on site when your adjuster inspects the roof to point out the damage we documented and answer construction questions. We don't negotiate the claim.
Your insurer sets the approved scope. If something is missing, we can document it in a supplemental estimate for your insurer to review.
We complete approved work, document closeout, and provide the closeout documents you need to request recoverable depreciation.
No. We document the roof damage and provide a contractor estimate. You file and manage the claim with your insurer. We're not a public adjuster.
No. Texas law prohibits contractors from paying or rebating your insurance deductible, and we follow the law.
You can still move forward with a repair or replacement on your own terms. We'll provide a clear estimate and options either way.
As soon as it's safe. Prompt documentation helps your claim and prevents further water damage. Call us for emergency tarping if needed.